
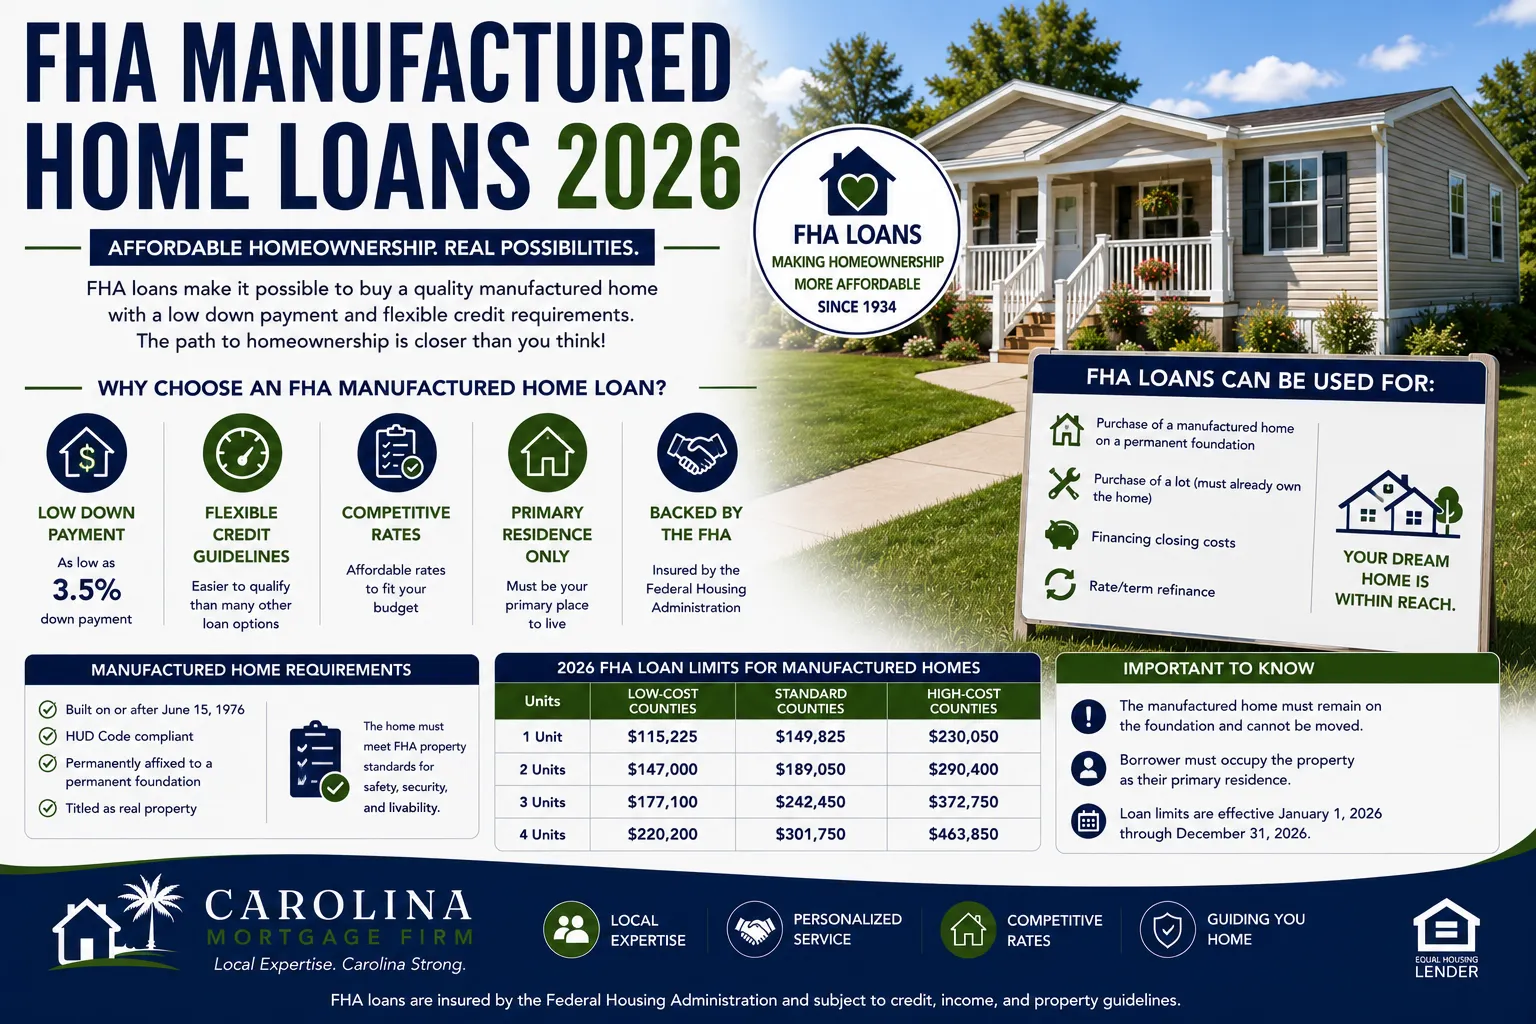
Manufactured homes continue to provide one of the most affordable paths to homeownership for many buyers throughout North and South Carolina.
With housing prices remaining elevated in many markets, manufactured homes offer an attractive alternative for buyers seeking affordability, flexibility, and homeownership opportunities.
One of the most common questions we hear at Carolina Mortgage Firm is:
“Can I use an FHA loan to buy a manufactured home?”
The answer is:
Yes, in many cases you can.
However, FHA has specific requirements that manufactured homes must meet before they can qualify for financing.
Understanding these requirements before shopping can save time, reduce frustration, and help you focus on properties that are likely to qualify.
Quick Answer: FHA and Manufactured Homes
FHA financing can be used to purchase a manufactured home when:
- The home meets FHA guidelines
- The property is considered real estate
- The home is permanently attached to the land
- The foundation meets FHA requirements
- The property serves as the borrower’s primary residence
Not every manufactured home qualifies, which is why reviewing the property early is important.
What Is a Manufactured Home?
A manufactured home is a home built in a factory and transported to its final location.
Homes built after June 15, 1976, are generally constructed according to standards established by the U.S. Department of Housing and Urban Development (HUD).
These homes typically display a HUD certification label, often referred to as a HUD tag. Manufactured homes are different from:
Modular Homes
Built in sections but generally treated similarly to site-built homes.
Mobile Homes
A term commonly used for homes built before modern HUD standards were implemented. For FHA purposes, understanding the distinction is important.
FHA Manufactured Home Requirements
To qualify for FHA financing, the manufactured home must generally meet specific requirements.
Permanent Foundation
One of the most important requirements is that the home must be permanently attached to an approved foundation system.
Temporary or non-permanent installations often do not qualify.
Real Property Classification
The home must typically be legally classified as real estate rather than personal property.
HUD Certification
The home must generally have required HUD certification labels and documentation.
Primary Residence
FHA loans are intended for owner-occupied properties. The home must serve as your primary residence.
Why Foundation Requirements Matter
Foundation issues are one of the most common reasons manufactured homes fail FHA financing. The foundation must generally:
- Be permanent
- Support long-term stability
- Meet HUD requirements
- Be properly engineered when necessary
Lenders and appraisers will review foundation conditions carefully.
If foundation concerns exist, additional inspections may be required.
Can I Buy the Land and Home Together?
Yes.
Many FHA manufactured home transactions involve:
The borrower purchases both the land and manufactured home together. This is often the easiest financing scenario.
Existing Manufactured Home on Owned Land
If the home is already permanently attached to land, financing may be available. Each situation should be reviewed individually.
Can FHA Finance New Manufactured Homes?
Often yes.
Many buyers throughout Lancaster, Pageland, Monroe, Clover, Chester, and surrounding communities choose newly manufactured homes placed on private land.
Benefits include:
- Lower purchase prices
- Modern floor plans
- Energy-efficient construction
- New home warranties
New manufactured homes can be an excellent alternative to traditional site-built housing.
Common Property Issues That Can Prevent FHA Approval
Not every manufactured home qualifies. Common concerns include:
Missing HUD Tags
Required identification labels may be unavailable.
Foundation Problems
Improper installation can create financing challenges.
Property Condition Issues
Major repairs may be required before closing.
Personal Property Classification
The home may not be legally converted to real estate.
Land Ownership Issues
Financing becomes more complex when land ownership is not clear. Reviewing these items early can prevent surprises.
FHA Manufactured Homes vs Conventional Financing
Both FHA and Conventional financing may be available.
FHA Advantages
- Lower down payment
- Flexible credit guidelines
- First-time buyer friendly
Conventional Advantages
- Potentially different mortgage insurance options
- Additional financing flexibility in some situations The best option depends on your specific circumstances.
Why Manufactured Homes Are Popular in the Carolinas
Manufactured homes remain especially popular throughout:
South Carolina
- Lancaster County
- Chester County
- York County
- Kershaw County
- Pageland Area
North Carolina
- Union County
- Anson County
- Stanly County
- Richmond County
- Rural Mecklenburg Outskirts
Many buyers choose manufactured homes because they provide:
- More land
- Lower purchase prices
- Rural living opportunities
- Reduced monthly payments
Common Manufactured Home Financing Myths
Myth #1: FHA Doesn’t Finance Manufactured Homes
False.
FHA financing is available for many manufactured homes.
Myth #2: Manufactured Homes Are Always Difficult to Finance
Not necessarily.
Homes meeting FHA guidelines can often be financed successfully.
Myth #3: Manufactured Homes Must Be Brand New
False.
Existing manufactured homes may qualify.
Myth #4: Manufactured Homes Never Appreciate
Property appreciation depends on numerous market factors and should not be generalized.
Why Pre-Approval Matters
Manufactured home financing often involves additional property review. Obtaining a pre-approval first provides several advantages.
Understand Financing Options
Compare FHA, Conventional, USDA, and VA financing.
Verify Budget
Know exactly what you can afford.
Avoid Non-Qualifying Properties
Focus on homes likely to meet lender requirements.
Move Quickly
Be ready when the right property becomes available.
Why Work With Carolina Mortgage Firm?
At Carolina Mortgage Firm, we help buyers throughout:
- Lancaster
- Rock Hill
- Indian Land
- Fort Mill
- Clover
- Chester
- Pageland
- Monroe
- Matthews
- Waxhaw
navigate manufactured home financing options. We compare:
- FHA Loans
- Conventional Loans
- USDA Loans
- VA Loans
- Down Payment Assistance Programs
to identify solutions that fit your goals and budget.
Frequently Asked Questions
Can FHA Loans Be Used for Manufactured Homes?
Yes, when FHA property requirements are met.
Does the Home Need a Permanent Foundation?
Generally yes.
Can I Buy Land and a Manufactured Home Together?
Often yes.
Do Manufactured Homes Qualify for FHA’s 3.5% Down Payment?
In many cases, yes.
Can Existing Manufactured Homes Qualify?
Absolutely, provided they meet FHA requirements.
Related FHA Resources
- What Credit Score Do I Need for an FHA Loan?
- FHA Down Payment Requirements
- FHA Gift Funds Requirements
- FHA Student Loan Guidelines
- FHA Loan Limits in North and South Carolina
Ready to Explore Manufactured Home Financing?
Whether you’re purchasing a manufactured home in Lancaster County, Monroe, Pageland, Chester, Clover, Rock Hill, or elsewhere throughout North and South Carolina, Carolina Mortgage Firm can help you understand your financing options and determine whether FHA financing is the right fit.
Contact our team today for a personalized mortgage consultation and FHA pre-approval.