
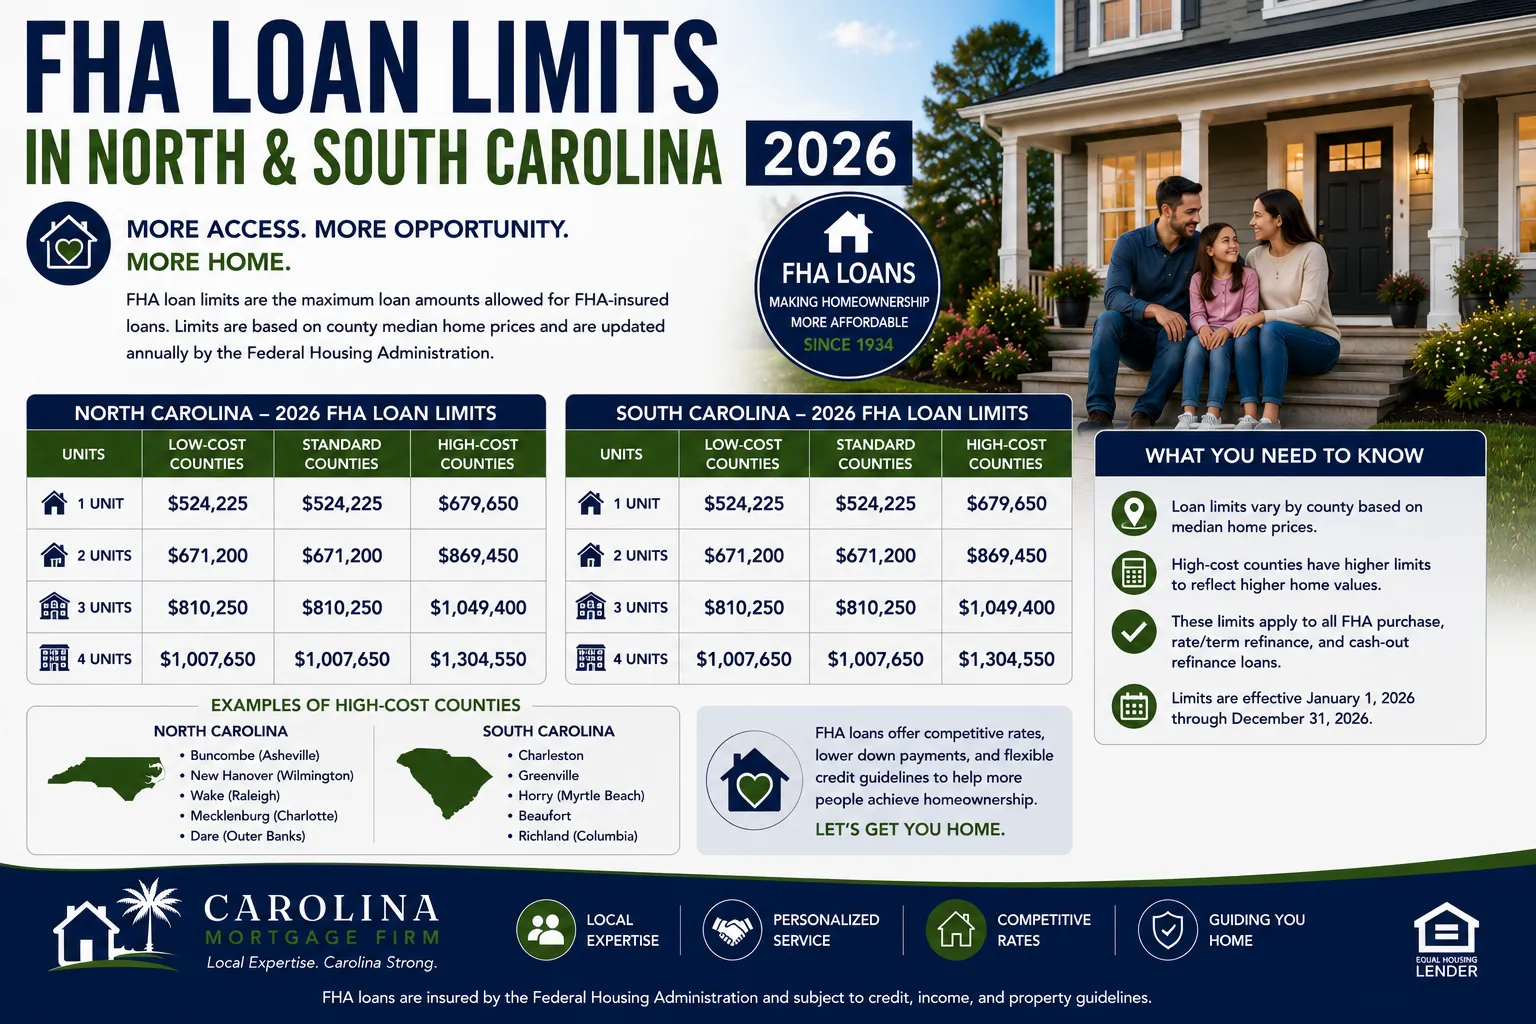
If you’re considering an FHA loan, one of the most important questions to understand is:
“How much can I borrow?”
The answer depends in part on FHA loan limits.
FHA loan limits establish the maximum loan amount that can be insured by the Federal Housing Administration for a specific county.
At Carolina Mortgage Firm, we help homebuyers throughout Charlotte, Fort Mill, Indian Land, Rock Hill, Lancaster, Matthews, Waxhaw, Belmont, Huntersville, and surrounding communities understand how FHA loan limits affect their purchasing power.
The good news is that FHA loan limits are often higher than many buyers expect, making FHA financing a viable option for a wide range of home prices throughout North and South Carolina.
Quick Answer: What Are FHA Loan Limits?
FHA loan limits are the maximum mortgage amounts FHA will insure for a property. These limits are determined annually and vary based on:
- County location
- Property type
- Local housing costs
- Number of units
Loan limits help ensure FHA financing remains available while reflecting local real estate markets.
Why FHA Loan Limits Exist
FHA was created to expand homeownership opportunities while maintaining responsible lending practices. Loan limits help:
Promote Affordable Homeownership
FHA primarily serves owner-occupied borrowers.
Reflect Local Housing Markets
Higher-cost areas may receive higher loan limits.
Manage Risk
Loan limits help maintain the long-term stability of the FHA program.
Because housing markets change over time, FHA reviews and adjusts limits periodically.
Do FHA Loan Limits Vary by County?
Yes.
FHA loan limits are established on a county-by-county basis. This means the loan limit in one county may differ from another. For example:
A county with higher home values may have a larger FHA loan limit than a county with lower average home prices.
This is particularly important for buyers searching across multiple counties in North and South Carolina.
Charlotte Metro FHA Loan Considerations
Many Carolina Mortgage Firm clients search throughout the greater Charlotte region, including:
North Carolina
- Mecklenburg County
- Union County
- Cabarrus County
- Gaston County
- Iredell County
- Lincoln County
South Carolina
- York County
- Lancaster County
- Chester County
Because FHA limits can vary by county, buyers should verify current limits before making purchasing decisions.
How FHA Loan Limits Affect Homebuyers
Loan limits influence:
Maximum FHA Loan Amount
The largest FHA-insured mortgage available.
Home Shopping Budget
Your target purchase price range.
Down Payment Requirements
Higher-priced homes may require additional funds.
Financing Strategy
Some buyers may compare FHA and Conventional financing depending on the purchase price. Understanding FHA limits early helps avoid surprises during the home search process.
FHA Loan Limits by Property Type
Many buyers are surprised to learn that FHA limits vary based on the number of units.
Single-Family Homes
One-unit primary residences.
Duplexes
Two-unit properties.
Triplexes
Three-unit properties.
Fourplexes
Four-unit properties.
Because multi-unit properties often cost more, higher FHA limits may apply. This is particularly beneficial for buyers pursuing house hacking strategies.
What If the Home Price Exceeds FHA Loan Limits?
If your desired home exceeds FHA loan limits, several options may still be available.
Larger Down Payment
Reducing the loan amount may keep the transaction within FHA limits.
Conventional Financing
Many buyers transition to conventional financing when purchasing higher-priced homes.
Jumbo Financing
For homes exceeding conforming loan limits.
Alternative Loan Programs
Depending on borrower qualifications and goals.
A mortgage consultation can help determine the most effective approach.
Are FHA Loan Limits the Same as Conforming Loan Limits?
No.
FHA loan limits and conventional conforming loan limits are separate programs with different rules. Both are adjusted periodically, but they serve different lending markets.
Understanding which program best fits your situation is an important part of the mortgage planning process.
Why FHA Loan Limits Matter for First-Time Homebuyers
Many first-time buyers assume FHA is only for lower-priced homes.
In reality, FHA financing can often accommodate a wide range of home values throughout the Carolinas. Benefits include:
Low Down Payment
As little as 3.5% down for qualified borrowers.
Flexible Credit Requirements
FHA remains one of the most accessible loan programs.
Multi-Unit Opportunities
Duplex, triplex, and fourplex financing may be available.
Competitive Financing
Many buyers find FHA provides an excellent path to homeownership.
Common FHA Loan Limit Myths
Myth #1: FHA Is Only for Cheap Homes
False.
Many moderately priced homes qualify for FHA financing.
Myth #2: FHA Loan Limits Are the Same Everywhere
False.
Limits vary by county.
Myth #3: FHA Can’t Finance Multi-Unit Properties
False.
FHA may finance properties with up to four units when occupancy requirements are met.
Myth #4: FHA Is Only for First-Time Buyers
False.
Repeat buyers frequently use FHA financing.
How to Determine Your Maximum FHA Loan Amount
Several factors influence qualification.
Income
Your income helps determine affordability.
Debt-to-Income Ratio
Monthly obligations affect borrowing power.
Credit Score
Impacts qualification and financing options.
Down Payment
Available funds affect purchasing power.
FHA County Limits
Establish the maximum FHA-insured loan amount.
A full pre-approval provides the most accurate estimate.
Why Pre-Approval Matters
Before shopping for homes, obtaining an FHA pre-approval provides several benefits.
Know Your Budget
Understand your purchasing power.
Verify FHA Eligibility
Confirm loan program options.
Review County-Specific Limits
Ensure your target area aligns with your goals.
Strengthen Offers
Sellers prefer serious, pre-approved buyers.
Why Work With Carolina Mortgage Firm?
At Carolina Mortgage Firm, we help buyers throughout:
- Charlotte
- Fort Mill
- Indian Land
- Rock Hill
- Lancaster
- Matthews
- Waxhaw
- Belmont
- Huntersville
- Concord
understand FHA loan limits and compare financing options. Because we work with multiple lenders, we can compare:
- FHA Loans
- Conventional Loans
- VA Loans
- USDA Loans
- Jumbo Financing
- Down Payment Assistance Programs
to help you choose the financing solution that best fits your goals.
Frequently Asked Questions
Do FHA Loan Limits Change Every Year?
They may be adjusted periodically based on housing market data.
Are FHA Loan Limits Different in North Carolina and South Carolina?
Yes, limits can vary by county.
Can FHA Be Used for Duplexes and Fourplexes?
Often yes, subject to occupancy requirements.
What Happens If My Home Price Exceeds FHA Limits?
Alternative financing options may be available.
How Do I Find Current FHA Limits?
A mortgage professional can provide the most current county-specific information.
Related FHA Resources
- What Credit Score Do I Need for an FHA Loan?
- FHA Down Payment Requirements
- FHA Gift Funds Requirements
- FHA Co-Borrower Guidelines
- Can FHA Loans Be Used for Investment Properties?
Ready to Explore FHA Financing?
Whether you’re buying a home in Charlotte, Fort Mill, Indian Land, Rock Hill, Lancaster, or anywhere throughout North or South Carolina, Carolina Mortgage Firm can help you understand FHA loan limits and determine the best financing strategy.
Contact our team today for a personalized FHA consultation and mortgage pre-approval.