
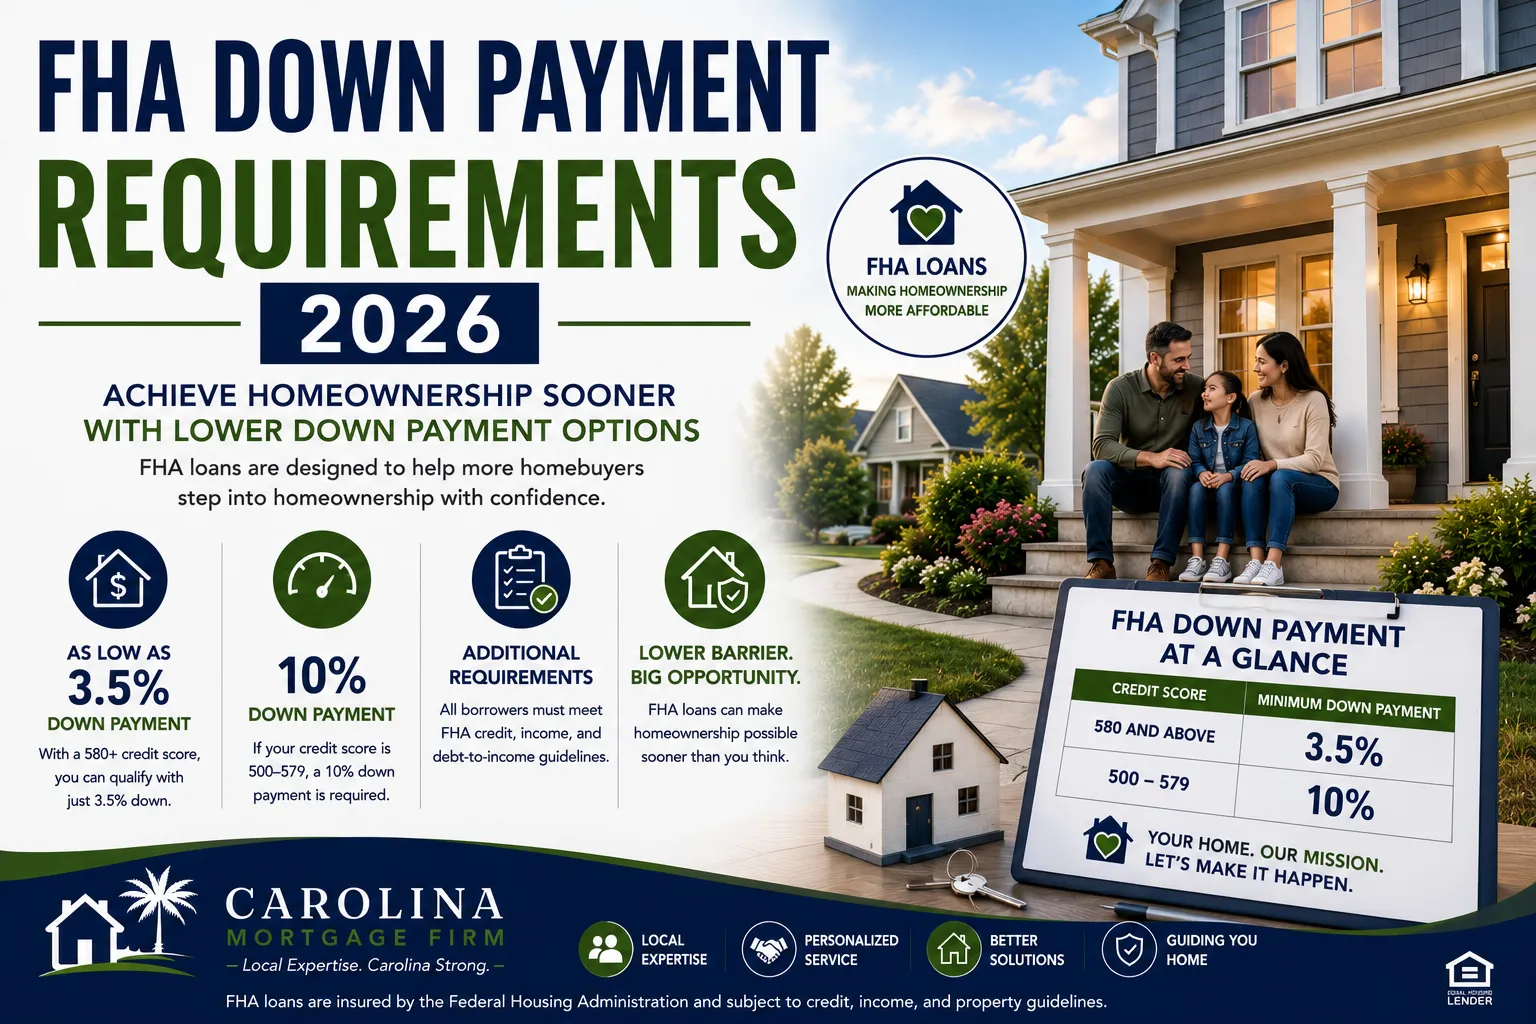
One of the biggest misconceptions about buying a home is that you need a 20% down payment.
The reality is that many homebuyers purchase homes with significantly less money down, especially when using an FHA loan.
At Carolina Mortgage Firm, one of the most common questions we hear from first-time homebuyers throughout Charlotte, Fort Mill, Indian Land, Rock Hill, Lancaster, Matthews, Waxhaw, and surrounding communities is:
“How much money do I need for an FHA down payment?”
The answer is often much less than buyers expect.
Let’s explore how FHA down payments work and what options are available to help you achieve homeownership sooner.
Quick Answer: FHA Down Payment Requirements
For most FHA loans:
Minimum Down Payment: 3.5%
Borrowers with qualifying credit scores can purchase a home with as little as 3.5% down. For example:
| Purchase Price | Minimum FHA Down Payment |
| $250,000 | $8,750 |
| $300,000 | $10,500 |
| $350,000 | $12,250 |
| $400,000 | $14,000 |
| $500,000 | $17,500 |
Compared to a traditional 20% down payment, FHA financing can dramatically reduce the amount of cash needed to purchase a home.
Why FHA Loans Were Created
The FHA loan program was designed to help more Americans achieve homeownership. Many buyers have:
- Strong income
- Stable employment
- Good payment history
but struggle to save large down payments.
By allowing lower down payments, FHA financing helps qualified buyers enter the housing market sooner. This is one reason FHA remains one of the most popular mortgage programs in the United States.
Do I Need 20% Down?
No.
This is perhaps the biggest myth in homeownership.
While putting 20% down can provide benefits, many buyers successfully purchase homes with:
- 3.5% down (FHA)
- 3% down (Certain Conventional programs)
- 0% down (VA and USDA loans for eligible borrowers)
Waiting years to save 20% may not always be the best strategy, especially if home prices continue to rise. A mortgage consultation can help determine the most appropriate option based on your goals.
Can Gift Funds Be Used for an FHA Down Payment?
Yes.
One of the most attractive features of FHA financing is the ability to use gift funds. Gift funds can often be used for:
- Down payment
- Closing costs
- Prepaid expenses
Many first-time buyers receive assistance from family members to help achieve homeownership.
Proper documentation is required, including a gift letter and verification of funds.
What Is a Gift Letter?
A gift letter is a document confirming that funds being provided are a gift rather than a loan. The letter typically includes:
- Donor information
- Recipient information
- Gift amount
- Relationship between parties
- Statement confirming repayment is not expected
Your mortgage advisor will help ensure proper documentation is obtained.
Can Down Payment Assistance Be Used With FHA Loans?
In many cases, yes.
Numerous down payment assistance programs are available throughout North and South Carolina. These programs may help cover:
- Down payment
- Closing costs
- Prepaid expenses
Some assistance programs are structured as:
- Grants
- Forgivable loans
- Deferred-payment loans
Eligibility varies based on program guidelines.
What Other Costs Should Buyers Expect?
The down payment is only one part of the homebuying process. Additional costs may include:
Closing Costs
Expenses associated with obtaining the mortgage.
Homeowners Insurance
Required by most lenders.
Property Taxes
Collected through escrow in many situations.
Prepaid Expenses
Items such as interest and insurance reserves.
The good news is that seller concessions and assistance programs may help offset some of these expenses.
Example FHA Purchase Scenario
Let’s assume a buyer purchases a home for:
$325,000
Minimum FHA Down Payment: 3.5% = $11,375
The buyer may also be able to use:
- Gift funds
- Down payment assistance
- Seller-paid closing costs
As a result, the amount of personal funds required may be less than many buyers expect.
Every situation is unique, which is why obtaining a personalized mortgage review is important.
FHA vs Conventional Down Payments
Many buyers compare FHA and Conventional financing.
FHA Loan
Minimum down payment often starts at 3.5%. Benefits include:
- Flexible qualification
- Lower credit score requirements
- First-time buyer friendly
Conventional Loan
Certain programs allow as little as 3% down. Benefits may include:
- Different mortgage insurance structures
- Potential long-term savings for qualified borrowers The right choice depends on your financial profile.
Common FHA Down Payment Myths
Myth #1: I Need 20% Down
False.
Most FHA borrowers purchase with 3.5% down.
Myth #2: The Down Payment Must Come From My Savings
False.
Gift funds and assistance programs may be available.
Myth #3: FHA Is Only for First-Time Buyers
False.
Many repeat buyers use FHA financing.
Myth #4: FHA Loans Are Difficult to Qualify For
Not necessarily.
FHA financing was designed to make homeownership more accessible.
How to Prepare for an FHA Down Payment
If you’re planning to buy a home in the next 6-12 months, consider:
Building Savings
Even modest monthly contributions add up.
Avoiding Large Unnecessary Purchases
Preserve funds for your home purchase.
Monitoring Your Credit
Stronger credit profiles often create more options.
Exploring Assistance Programs
Many buyers qualify for programs they didn’t know existed.
Why Pre-Approval Matters
The best way to determine exactly how much money you’ll need is through a mortgage pre-approval. Benefits include:
Understanding Your Budget
Know what price range makes sense.
Reviewing Loan Options
Compare FHA, Conventional, VA, and USDA financing.
Identifying Assistance Programs
Discover available grants and assistance opportunities.
Shopping With Confidence
Know exactly where you stand before looking at homes.
Why Work With Carolina Mortgage Firm?
At Carolina Mortgage Firm, we help buyers throughout:
- Charlotte
- Fort Mill
- Indian Land
- Rock Hill
- Lancaster
- Matthews
- Waxhaw
- Belmont
- Huntersville
- Concord
understand down payment requirements and identify programs that may reduce upfront costs. We compare:
- FHA Loans
- Conventional Loans
- VA Loans
- USDA Loans
- Down Payment Assistance Programs
to help buyers choose the financing solution that best fits their goals.
Frequently Asked Questions
What Is the Minimum FHA Down Payment?
Typically 3.5% of the purchase price.
Can I Use Gift Funds?
Yes, with proper documentation.
Can Down Payment Assistance Be Combined With FHA?
Often yes.
Do I Need 20% Down?
No.
Can FHA Be Used by Repeat Buyers?
Absolutely.
Related FHA Resources
- What Credit Score Do I Need for an FHA Loan?
- Can Gift Funds Be Used for an FHA Loan?
- Can I Have a Co-Borrower on an FHA Loan?
- FHA Student Loan Guidelines
- FHA Loan Limits in North and South Carolina
Ready to Explore FHA Financing?
Whether you’re buying your first home in Charlotte, moving to Fort Mill, relocating to Indian Land, purchasing in Rock Hill, or searching throughout Lancaster County, Carolina Mortgage Firm can help you understand your FHA options and determine exactly how much money you’ll need to buy a home.
Contact our team today for a personalized mortgage consultation and FHA pre-approval.