
One of the most common questions homebuyers ask is:
“What credit score do I need to qualify for an FHA loan?”
The good news is that FHA loans were specifically designed to help borrowers achieve homeownership even if they don’t have perfect credit.
At Carolina Mortgage Firm, we work with buyers throughout Charlotte, Fort Mill, Indian Land, Rock Hill, Lancaster, Matthews, Waxhaw, and surrounding communities who are often surprised to learn they may qualify for an FHA loan sooner than they expected.
While credit scores are important, they are only one piece of the mortgage approval process. Income, employment history, assets, and overall financial stability also play important roles.
Let’s take a closer look at FHA credit score requirements and how they may affect your homebuying journey.
Quick Answer: FHA Credit Score Requirements
For most FHA loans:
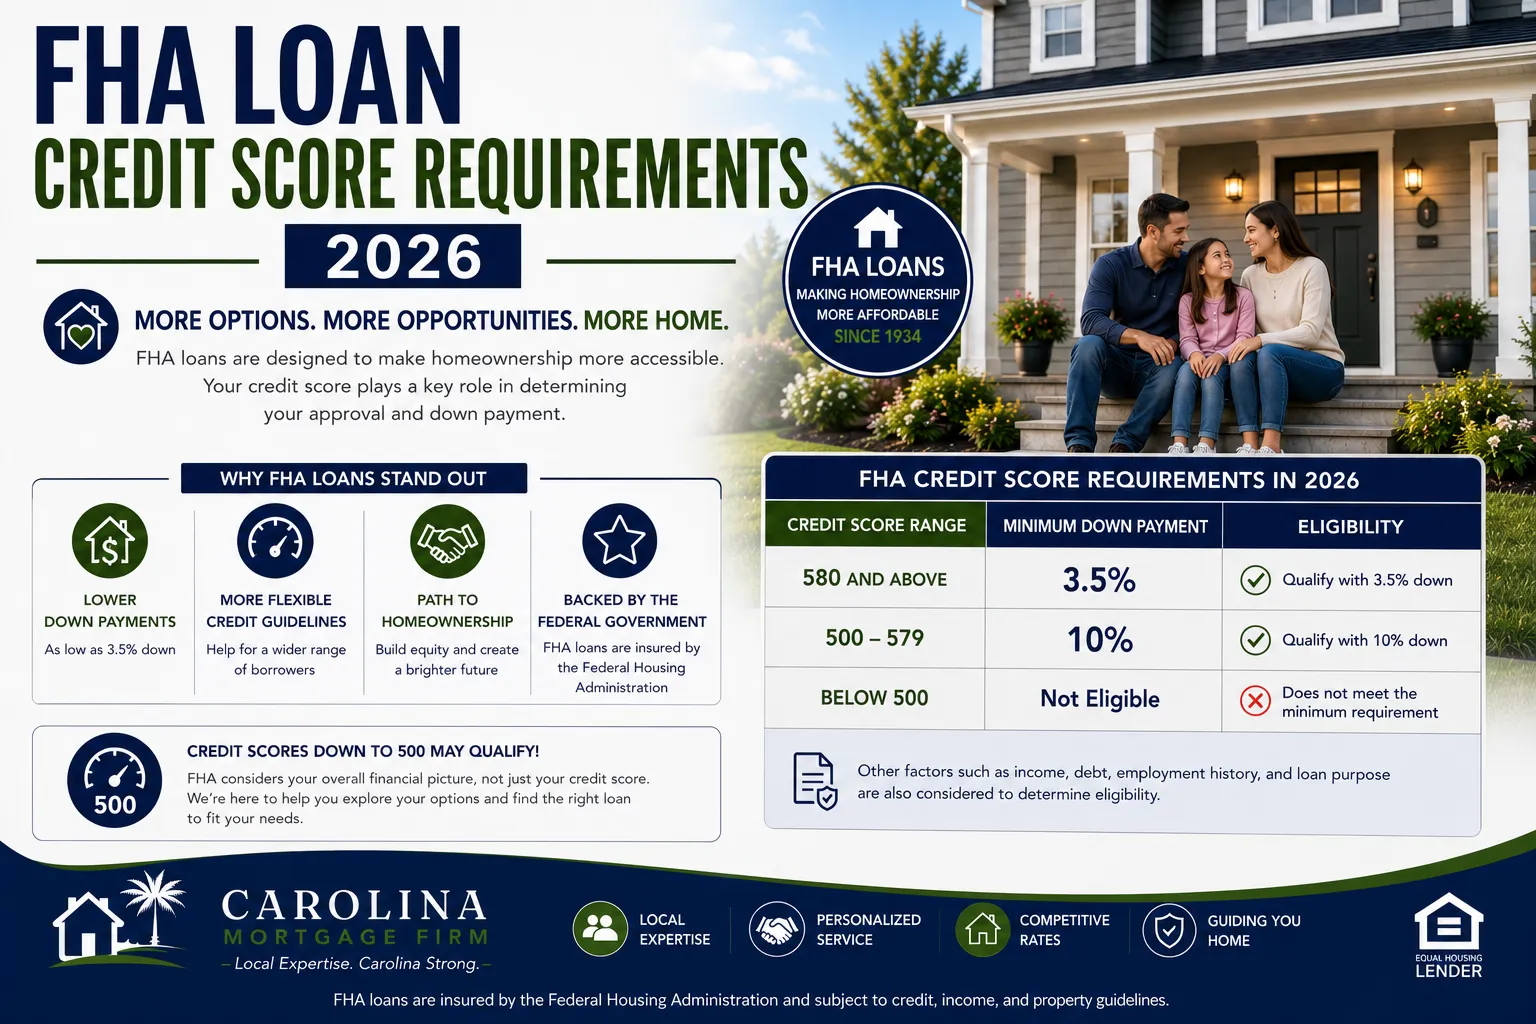
580 Credit Score or Higher
Borrowers with a credit score of 580 or above may qualify for FHA financing with the minimum required down payment of 3.5%.
500 to 579 Credit Score
Borrowers with credit scores between 500 and 579 may still qualify under FHA guidelines, but a larger down payment may be required.
Below 500 Credit Score
Borrowers below 500 generally do not qualify for FHA financing.
It’s important to understand that while FHA establishes these minimum guidelines, individual lenders may have additional requirements known as “overlays.”
Why FHA Loans Are Popular for First-Time Homebuyers
FHA loans are often considered one of the most accessible mortgage options available. Benefits include:
- Lower down payment requirements
- Flexible credit guidelines
- Competitive interest rates
- Gift funds allowed
- Higher debt-to-income flexibility
Because of these advantages, FHA financing remains one of the most popular options for first-time homebuyers throughout North and South Carolina.
How Credit Scores Affect FHA Loans
Many borrowers assume FHA approval is based solely on a credit score. That is not true.
Your credit score helps lenders evaluate risk, but underwriters also review:
Payment History
Have you made your obligations on time?
Collection Accounts
Certain collections may require additional review.
Bankruptcies
Past bankruptcies do not automatically disqualify borrowers.
Foreclosures
Waiting periods may apply, but future homeownership is often possible.
Overall Credit Profile
Lenders look at the complete picture rather than a single number.
A borrower with a 620 score and strong financial habits may be viewed differently than a borrower with a similar score and recent credit issues.
What If My Credit Score Is Below 580?
Many buyers believe they must wait years before qualifying for a mortgage. Often, that’s not the case.
If your score is below 580, there may be opportunities to improve it relatively quickly. Common strategies include:
Paying Down Credit Card Balances
Reducing credit utilization can often have a positive impact.
Correcting Credit Report Errors
Reviewing your credit report for inaccuracies is important.
Making All Payments On Time
Consistent payment history is one of the most significant scoring factors.
Avoiding New Debt
Opening new accounts can temporarily impact scores.
Many buyers are surprised by how much improvement can occur within several months.
FHA Credit Scores vs Conventional Loans
Many buyers compare FHA financing with Conventional financing. Generally speaking:
FHA Loans
Often provide greater flexibility for borrowers with lower credit scores.
Conventional Loans
May offer lower overall borrowing costs for borrowers with stronger credit profiles. This is why we often compare both options before making recommendations.
Sometimes FHA is clearly the better choice.
Other times, Conventional financing may provide long-term savings.
What Credit Score Gets the Best FHA Interest Rate?
While FHA loans remain available across a range of credit profiles, higher scores often receive more favorable pricing.
Generally:
580-619
May qualify but could receive less favorable pricing.
620-679
Often provides improved loan options.
680-739
Typically viewed favorably by lenders.
Often receives the strongest available pricing.
Even if your score is not perfect, FHA financing may still provide an excellent path to homeownership.
Common FHA Credit Score Myths
Myth #1: I Need Perfect Credit
False.
Many FHA borrowers purchase homes with scores well below what people consider “perfect.”
Myth #2: One Late Payment Means Automatic Denial
False.
Lenders evaluate the overall credit profile.
Myth #3: Collections Automatically Disqualify Me
Not necessarily.
Each situation is reviewed individually.
Myth #4: I Should Wait Until My Score Is 700
Not always.
Many buyers qualify long before reaching a 700 score.
Waiting may cause you to miss opportunities if home prices continue rising.
Other Factors Lenders Consider
Even with an acceptable credit score, lenders review additional factors.
Income
Stable and documentable income is important.
Employment
Consistent employment history strengthens a mortgage application.
Assets
Lenders review available funds for down payment and closing costs.
Debt-to-Income Ratio
Monthly obligations must fit within program guidelines.
Because mortgage approval involves multiple factors, a full pre-approval review provides the most accurate answers.
Why Pre-Approval Matters
The fastest way to determine whether you qualify is through a mortgage pre-approval. Benefits include:
Understanding Your Options
Compare FHA, Conventional, VA, and USDA financing.
Identifying Improvement Opportunities
Know exactly what changes could strengthen your application.
Establishing a Budget
Understand how much home fits your goals.
Shopping With Confidence
Know your financing has already been reviewed.
Many buyers discover they are closer to homeownership than they expected.
Why Work With Carolina Mortgage Firm?
At Carolina Mortgage Firm, we help buyers throughout:
- Charlotte
- Fort Mill
- Indian Land
- Rock Hill
- Lancaster
- Matthews
- Waxhaw
- Belmont
- Huntersville
- Concord
understand their credit profile and compare mortgage options. Because we work with multiple lenders, we can compare:
- FHA Loans
- Conventional Loans
- VA Loans
- USDA Loans
- Down Payment Assistance Programs
to help identify the financing strategy that best fits your goals.
Frequently Asked Questions
Can I Get an FHA Loan With a 580 Credit Score?
In many cases, yes.
Can I Get an FHA Loan With a 600 Credit Score?
Often yes, provided other qualification requirements are met.
What If My Score Is Below 580?
There may be steps you can take to improve your score and qualify.
Does FHA Require Perfect Credit?
No.
Should I Apply Even If I’m Unsure?
Absolutely. A pre-approval review provides clarity and often identifies opportunities you may not realize exist.
Related FHA Resources
- How Much Down Payment Is Required for an FHA Loan?
- Can Gift Funds Be Used for an FHA Loan?
- How Are Student Loans Calculated for FHA Loans?
- Can I Have a Co-Borrower on an FHA Loan?
- FHA Loan Limits in North and South Carolina
Ready to Find Out If You Qualify?
Whether you’re buying your first home in Charlotte, relocating to Fort Mill, purchasing in Indian Land, moving to Rock Hill, or searching throughout Lancaster County, Carolina Mortgage Firm can help you evaluate your credit profile and explore FHA financing options.
Contact our team today for a personalized FHA eligibility review and mortgage pre-approval.